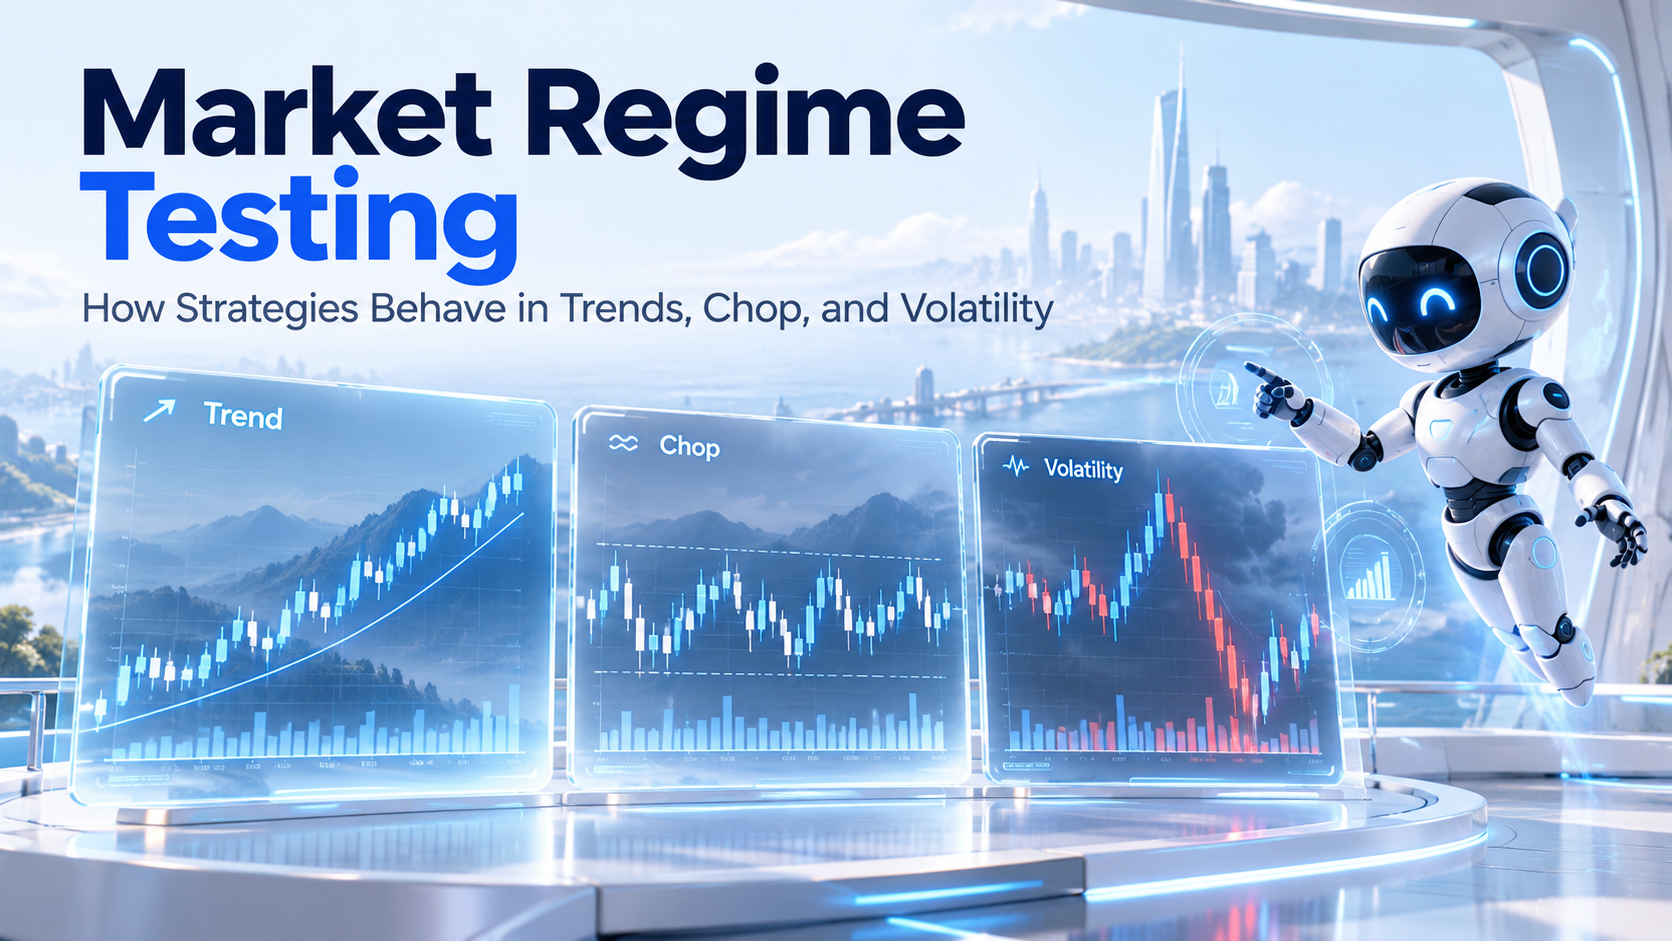
Market Regime Testing: How Strategies Behave in Trends, Chop, and Volatility
A strategy can produce an impressive backtest over several years and still have a serious weakness that is difficult to see in the final performance summary. The strategy may have earned most of its returns during one unusually favourable market period, while spending the rest of the test moving sideways, losing slowly, or struggling to find worthwhile trades.
This is easy to miss when we focus on the full-period return, maximum drawdown, and an equity curve that finishes higher than it started. Those numbers describe the combined outcome, but they do not always explain where the performance came from. A breakout strategy may have benefited disproportionately from one strong trend. A mean reversion strategy may have done most of its work while prices repeatedly bounced within a range. A long-only strategy may owe much of its historical performance to a prolonged rising market.
The important question is whether that dependence was understood before the result was accepted. If a strategy works well in one environment and struggles in another, the difference can be useful information. It tells us something about the idea, the conditions it relies on, and the assumptions we should test before deploying it.
This is the purpose of market regime testing. Instead of treating several years of historical data as one uniform period, we examine how a strategy behaves as market conditions change.
What Is a Market Regime?
A market regime is a broad description of the way a market behaves during a particular period. It is not necessarily a formal label supplied by an exchange or a single technical indicator. Traders commonly describe regimes in terms of direction, volatility, and the degree to which price movement persists or reverses.
In a sustained uptrend, price generally moves higher over time, although there may be sizeable pullbacks along the way. A downtrend has the opposite broad direction, but its trading behaviour may differ from an uptrend because declines can be accompanied by abrupt rebounds, gaps, or changes in liquidity. Sideways or choppy markets lack consistent direction and may alternate between short advances and reversals. High-volatility periods involve larger fluctuations, while low-volatility periods may bring narrower ranges and fewer meaningful moves.
These descriptions can overlap. A market can be trending and volatile at the same time. It can also move sideways with violent swings rather than with calm, narrow price action. That is why classifying a market into a single neat category can be misleading.
Regimes are also easier to identify after they have happened. A historical chart may make the beginning of a trend look obvious, while a live trader at that point would have had no certainty that the movement would continue. Any regime filter used in a live strategy must rely on information that was available at the time, not on a label applied with hindsight.
Why the Full Backtest Can Hide Regime Dependence
Imagine a breakout strategy tested across five years. The full backtest shows a positive return and a reasonably smooth recovery from drawdowns. Looking only at the end result, the strategy might appear consistent enough to consider for the next stage of validation.
Now divide that history into individual years. You discover that most of the profit came from one period of sustained directional movement. During several other years, the strategy generated repeated false breakouts, paid transaction costs, and contributed little or nothing to the final return.
That does not automatically mean the strategy has failed. A trend-dependent system may be expected to struggle when markets do not trend. The problem arises when its full-period performance is presented as though it were evidence of consistent performance across all conditions.
The same issue can affect other strategy types. A mean reversion system may perform well during extended ranges and then give back substantial gains when prices break out and continue moving. A volatility breakout system may perform differently during quiet periods compared with sudden volatility expansion. Even two versions of the same idea, tested on different timeframes, may respond very differently to the same market environment.
Breaking down the history helps separate two questions. Did the strategy produce a positive overall result? And what market conditions were responsible for that result? A trader needs both answers to form reasonable expectations.
Different Strategies Have Different Dependencies
Trend Following
Trend following strategies generally seek to participate in directional movement that persists long enough to overcome entries, exits, and trading costs. They may perform well during sustained trends but struggle when prices repeatedly reverse before a move develops.
This means a weak result during a choppy period may be consistent with the strategy's design. It should still be examined, especially if the losses are larger or more frequent than expected. But the presence of those losses does not, by itself, invalidate the underlying idea.
Mean Reversion
Mean reversion strategies look for price movements away from a reference level and test whether prices tend to move back toward it. They may find more opportunities in oscillating markets, although strong directional movement can make an apparently stretched price continue moving farther from its average.
A strategy that repeatedly buys weakness, for example, may struggle during a sustained decline. Regime review can show whether such periods produce manageable losses or expose a weakness in its exits and risk controls.
Breakout And Volatility Strategies
Breakout strategies seek to participate when price moves beyond a defined range or threshold. Some depend on follow-through after the initial move, while others are especially sensitive to a change from quiet to active trading.
A breakout signal in a low-volatility period may lead to a sustained movement, or it may simply reverse back into the range. Studying both outcomes across different conditions helps show whether the strategy depends on volatility expansion, directional persistence, or a particular combination of the two.
These are tendencies to investigate, not universal rules. Market behaviour, instrument choice, timeframe, order execution, and risk management can all change the result.
How to Review a Strategy Across Market Regimes
A useful regime review begins with a fixed version of the strategy. Keep the entry rules, exits, risk settings, and cost assumptions unchanged while you examine different periods. If you optimise the rules separately for every regime, it becomes difficult to tell whether you are learning about the strategy or merely fitting it to historical conditions.
Divide the History Into Meaningful Periods
Start by identifying periods that represent different conditions within your test data. These might include sustained advances, declines, sideways markets, calm sessions, and high-volatility episodes. Use a consistent method for identifying them, and document where each period begins and ends.
For a basic educational review, descriptive historical periods may be sufficient. If you intend to automate regime selection or switch strategies based on regime labels, the classification method needs a more rigorous test. It must use only information available when the decision would have been made.
Keep the sample size in mind. A short, highly unusual period with only a handful of trades provides limited evidence. A long period with many trades can be more informative, but it still represents only the market conditions that occurred in that sample.
Compare the Metrics Within Each Period
Once the periods are defined, review more than return. Compare trade count, average trade, average win and loss, profit factor, drawdown, losing streaks, and holding time. Include fees and slippage wherever they are part of the backtest assumptions.
Drawdown is especially valuable because two periods with similar returns can have very different risk profiles. A strategy might recover quickly from small setbacks in one regime but remain underwater for much longer in another. Trade count also matters because an apparently successful regime with very few trades may be less convincing than the headline performance suggests.
Make sure the comparisons are fair. A three-month period and a two-year period should not be judged by total profit alone. Differences in exposure, duration, trade opportunities, and capital allocation can distort the interpretation.
Review the Trades Behind the Summary
Summary metrics can tell you that one period was weak, but individual trades can help explain why. Review whether signals arrived later than expected, whether false entries clustered together, whether stops were hit more frequently, or whether winners were being cut short.
For example, if a trend strategy loses repeatedly in sideways markets, inspect how often price reversed soon after entry. If a mean reversion strategy struggles in a decline, review whether it repeatedly entered before the downward movement had exhausted itself. These observations can lead to useful research questions without immediately justifying a new filter.
Pay Attention to Regime Changes
One of the more difficult periods for any strategy can be the transition between market environments.
A market may shift from a persistent trend into a range, or from low volatility into a sharp directional move. A strategy designed around yesterday's conditions may continue generating signals while the character of the market is changing. Because transitions are uncertain in real time, they are also easy to misrepresent in historical analysis.
This is an important distinction. It is one thing to observe that a strategy performed well during a period subsequently labelled a strong uptrend. It is another to claim that the strategy could have identified the beginning of that uptrend and adjusted its behaviour immediately.
If you add a regime filter, inspect when that filter would actually have changed state. Did it use a completed candle? Did it rely on a moving average or volatility measure that updates with a delay? Did the backtest apply a future regime label to earlier trades? These timing questions can determine whether the apparent improvement is realistic.
The Danger of Optimising Away Every Weak Period
Once you know where a strategy struggled, it is tempting to add rules that would have removed those losses. A trend filter may remove a choppy year. A volatility threshold may avoid a difficult month. Another condition may eliminate a handful of particularly poor trades.
Some of these changes may improve a strategy for valid reasons. But repeated adjustments based on the same historical periods can produce overfitting. The strategy may become highly specialised at avoiding events that have already happened, without gaining the ability to handle future conditions.
A more disciplined approach is to treat regime review as a way of forming hypotheses. If you believe a filter addresses a genuine weakness, define the filter clearly, keep the original strategy as a comparison, and test the revised version on data that was not used to design the change.
It is also worth testing nearby settings and alternative periods. A filter that works only at one exact threshold or during one selected year deserves more scepticism than one that behaves reasonably across several tests.
The objective is not to erase every losing period from the historical chart. It is to understand the conditions under which the strategy may be vulnerable and decide whether those risks fit your trading plan.
What to Do With the Findings
A useful regime review should produce a written description of the strategy's behaviour, including where it appeared strong, where it struggled, and how much confidence the available sample supports.
That description can inform several decisions. It may change how you think about position sizing, the conditions that justify a closer review, or the range of drawdowns you should be prepared for. It may also tell you that an idea is worth testing only in a narrower set of conditions, or that its apparent strength depends too heavily on one historical episode.
However, recognizing a favourable historical regime is not the same as being able to identify it reliably in advance. If a strategy will be activated, paused, or resized according to market conditions, those rules need their own backtests, out-of-sample validation, and forward observation. Otherwise, regime analysis can simply become another source of hindsight bias.
The findings should also be revisited as new data accumulates. Historical relationships can weaken, and correlations between market behaviour and strategy returns are not permanent.
How FlyTradr Fits Into the Workflow
A structured testing environment can make regime review easier to repeat. In FlyTradr, the Strategy Builder helps turn a trading idea into explicit rules, while the Backtesting Lab provides historical results that can be reviewed across selected periods and strategy variations.
The Simulator can support a closer inspection of how a strategy behaves during particular historical conditions. Instead of relying only on the final equity curve, traders can examine the sequence of market movements and strategy decisions during stronger and weaker periods. The Paper Trader provides an additional opportunity to observe the strategy on current market data before considering live deployment.
None of these steps guarantees that a strategy will adapt successfully when the market changes. Their value is in making the assumptions clearer and the validation process more deliberate. The decision to change a rule, add a filter, reduce exposure, or continue testing should follow from evidence rather than the desire to improve one historical performance chart.
The Bottom Line
A positive full-period backtest is useful, but it is not the complete story of a strategy. The result may depend heavily on whether the test included sustained trends, sideways trading, volatility expansion, or other conditions that favoured the underlying logic.
Market regime testing helps reveal those dependencies. It encourages traders to compare performance across different environments, examine weak periods instead of hiding them, and question whether a proposed improvement will remain useful on fresh data.
A strategy does not need to perform equally well in every market condition to deserve further research. It does need a risk profile and a set of assumptions that are understood. The more clearly you can explain when an idea worked, when it struggled, and why those differences may have occurred, the better prepared you are to test it honestly going forward.
Comments
Ask a question or leave feedback. Guests can post too.
Max 2000 characters.
No comments yet.
Quick answers
What is this article about?
A promising backtest can depend heavily on one market environment.
Who should read this article on Market Regime Testing: How Strategies Behave in Trends, Chop, and Volatility?
This article is for retail traders who want a practical understanding of market regime testing: how strategies behave in trends, chop, and volatility before moving into backtesting, simulation, paper trading, or broker-connected execution.
What should I do after reading this article?
Use the article to clarify the concept first, then review FlyTradr workflow pages such as the algo trading platform overview, methodology and assumptions, or the FAQs page before making a platform decision.