
Survivorship Bias in Backtesting: Are You Testing Only Today's Winners?
Imagine testing a stock-selection strategy over ten years of market data. You start with a list of companies currently included in a major index, collect their historical prices, and apply your rules. The results look promising. The equity curve is reasonably smooth, drawdowns appear manageable, and the strategy seems to identify strong companies consistently.
There is a question that may never appear in the performance report. Were those the companies a trader could actually have selected from at every point during the test?
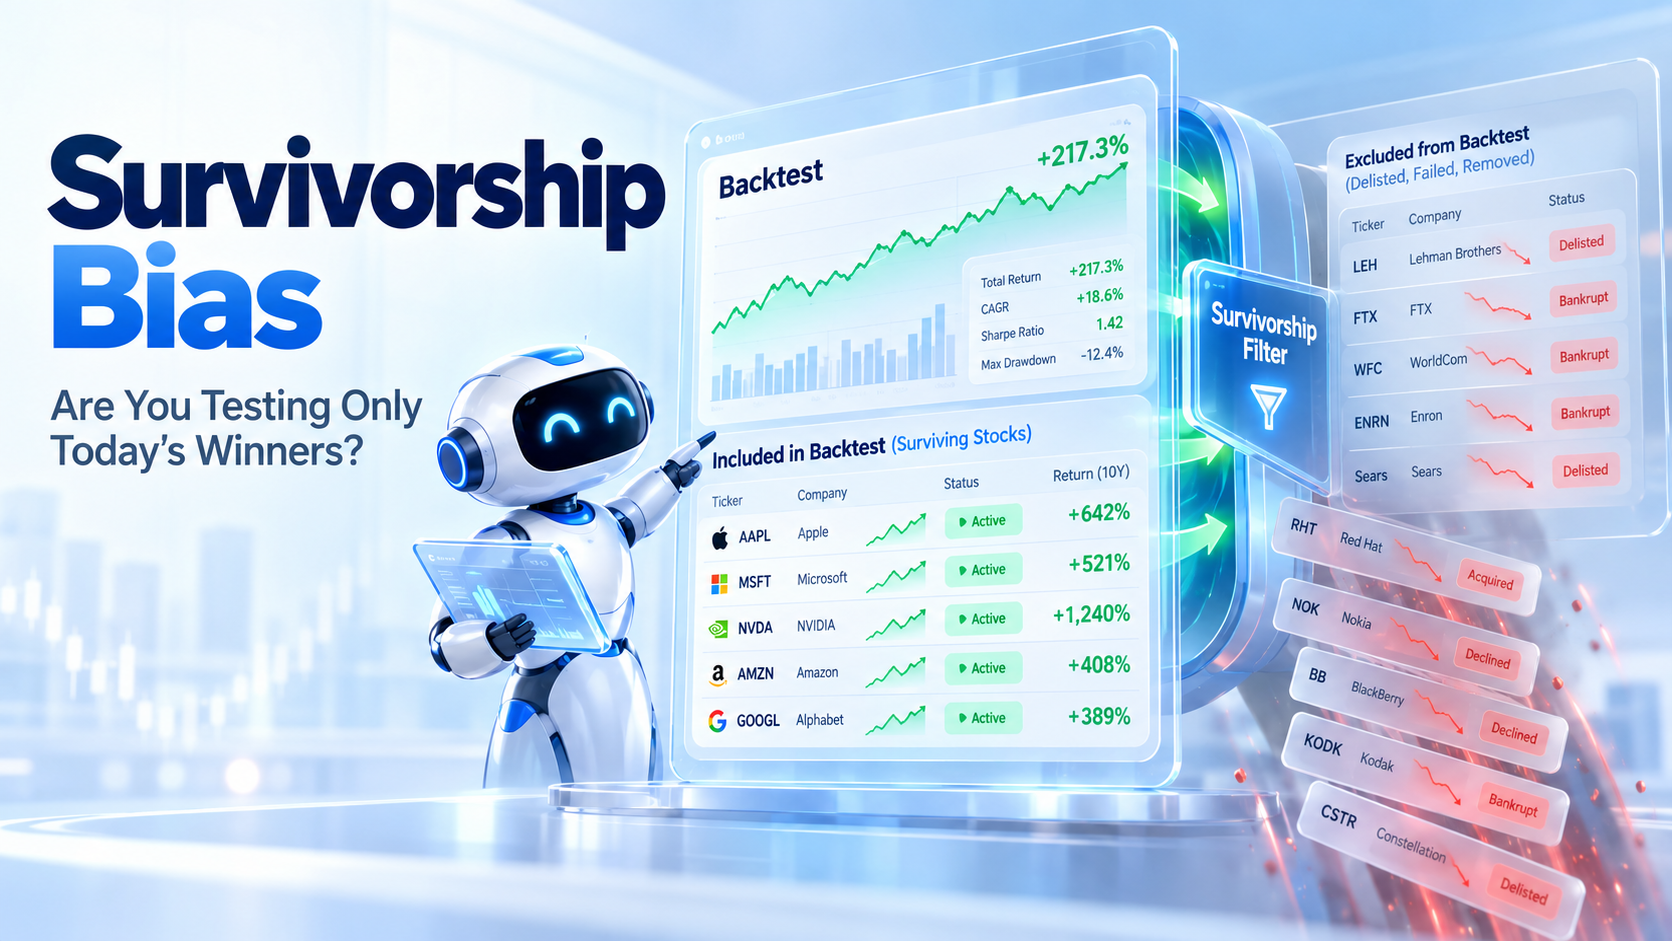
Some of today's index constituents may not have been members ten years ago. Meanwhile, companies that were previously included may have declined, been removed, merged, or delisted. If those historical companies are missing from your test, you may be evaluating a version of the past that has already been filtered by what happened afterward.
This is survivorship bias. It is a data selection problem that can make historical performance appear more convincing than the evidence really supports, even when the trading rules themselves are clearly defined.
What Survivorship Bias Means
Survivorship bias occurs when an analysis includes the instruments that remain in a dataset but overlooks those that disappeared or were excluded along the way. In an equity backtest, this often means testing currently listed companies without properly representing stocks that stopped trading or left the research universe during the historical period.
Consider an investor choosing stocks several years ago. They did not know which companies would survive, grow, be acquired, or remain eligible for an index in the future. They had to choose from the securities available at that time, including businesses that would later disappoint.
A historically faithful strategy test should respect that uncertainty. If a strategy claims to select from index members each month, its candidate list should reflect the membership applicable to each historical month, rather than today's membership applied retrospectively.
Survivorship bias is closely related to lookahead bias, but the terms are not interchangeable. Lookahead bias broadly involves using information that was unavailable at the decision point. Survivorship bias concerns which observations are included in the sample. Using a list of today's surviving constituents in earlier periods can create both problems.
Why It Can Distort Historical Performance
A backtest can only trade the instruments that its dataset contains. If companies that failed or were delisted are absent, the strategy may avoid exposure to some of the market's weaker outcomes without ever making a real decision to avoid them.
This can overstate historical returns, understate drawdowns, or create an overly reassuring picture of consistency. But the effect is not identical in every dataset. Companies leave indexes for different reasons, including acquisitions and changes in eligibility, and excluding a particular company does not always make returns look better.
The key issue is that the test is answering the wrong question. A backtest using today's surviving index members shows how the rules would have behaved on that selected group of companies over their historical price series. That is different from testing how the rules would have behaved on the index membership actually available at each earlier date.
Both exercises may be useful for research. They should not be described as though they are the same.
An Example Using The Nifty 50
Suppose you are developing a momentum strategy that ranks Nifty 50 constituents monthly and selects a few of the strongest stocks. You download the current constituent list and ten years of historical prices, then apply the ranking rule throughout that period.
The strategy may use only prior returns to calculate momentum, so the signals themselves appear free from future price data. Yet the universe is still problematic. A company that joined the index several years into the test might be included in your ranking candidates from the beginning. A company that was a constituent during an earlier year but subsequently exited the index might be missing completely.
For a strategy specifically designed around Nifty 50 membership, the more defensible method is to reconstruct the constituent universe for each historical selection date. A company should become eligible when it meets the strategy's index-membership rule, and former constituents should be represented during the periods in which they were eligible.
If your strategy instead selects from all eligible exchange-listed equities, the universe needs a different definition. The important part is to define the rule first and reconstruct its historical opportunity set accordingly.
Where Survivorship Bias Commonly Appears
Index Constituent Backtests
Indexes regularly change their membership. A test that uses today's constituent list for an earlier decade can exclude former members and include later additions before they were eligible. This matters for stock selection, ranking, momentum, rotation, and relative-strength systems.
Curated Watchlists
A watchlist assembled today may reflect years of attention to successful or familiar companies. When that list is applied to the past, its composition may already contain hindsight. Each company can have valid historical prices while the overall sample remains biased.
Historical Databases
Some providers focus primarily on active tickers. Delisted securities, older identifiers, and companies affected by mergers or corporate actions may have incomplete coverage. If missing symbols simply disappear from a backtest, a serious historical outcome can be mistaken for an absence of data.
Other Asset Classes
The same issue can affect cryptocurrency datasets and other markets. Testing a set of tokens or trading pairs that are active today may omit instruments that ceased trading. The underlying question is whether the dataset reflects the opportunities that were actually available when the strategy would have traded.
Why Better Strategy Rules Do Not Solve The Problem
A trader may spend hours improving entry conditions, stop placement, and exit logic while overlooking the selection universe. Yet a logically consistent strategy can still produce a misleading result if the instruments in the test were chosen using knowledge of future survival.
Improving an indicator does not restore a delisted stock that was left out of the database. Adding another filter does not correct historical index membership. These are data problems, not trading-rule problems, and they need separate attention.
This is why data quality belongs in the validation process alongside transaction costs, signal timing, slippage, and overfitting. Before refining a result, it is worth checking whether the test actually represents the market it claims to represent.
How To Review Your Historical Universe
Start by writing down the strategy's intended universe. Is it a fixed list chosen on a particular date, the constituents of an index at each rebalance, all qualifying exchange-listed stocks, or one specified instrument? These definitions require different historical data.
Next, find out how membership changes are handled. If the strategy uses an index, are historical constituent lists available? If it scans a broader market, does the database include securities that were delisted or became inactive during the test? If a stock changed ticker or merged with another company, how was its history carried forward?
Corporate actions and terminal events deserve attention too. A suspended or delisted holding should not simply vanish from the simulation without a documented accounting treatment. The prices, positions, and cash effects need to be handled in a way that matches the assumptions of the test.
Finally, record what you know and what you do not. A good research note can state which universe was used, how it was constructed, whether inactive instruments were included, and which limitations remain. This is far more useful than presenting a clean equity curve without explaining the dataset behind it.
What If Point-In-Time Data Is Unavailable?
For many retail traders, complete historical constituent lists and delisted-security datasets are difficult to obtain. That does not make every test worthless, but it should change how confidently the result is interpreted.
If you tested only today's constituents, describe the result that way. Do not present it as though the strategy selected from the historical index membership at each point in time. Where possible, compare results across different available universes and review whether the apparent performance depends heavily on a small set of eventual winners.
You can also evaluate the finished strategy on data that was not used during development, then observe it on a clearly specified current universe in paper trading. These steps provide additional evidence about subsequent behaviour. They do not repair the missing companies in an older historical test, and they should not be presented as a substitute for point-in-time data.
The useful habit is to keep the limitation visible and match the conclusion to the evidence.
Does This Matter For Every Strategy?
Survivorship bias is especially important for strategies that rank, screen, or select among many instruments. In those systems, the available candidate universe directly affects which trades can appear in the backtest.
For a strategy intentionally developed for one named instrument, historical constituent membership may be less central because the test does not claim to reconstruct a broad selection process. Even then, the reason that instrument was chosen deserves scrutiny. If a trader tested only today's most successful stocks and highlighted the strongest result, the research process can still contain selection bias.
It helps to distinguish the quality of the backtest for a chosen instrument from the quality of the method used to choose that instrument in the first place.
How FlyTradr Fits Into The Workflow
FlyTradr helps traders convert ideas into defined rules and examine their historical behaviour. The Strategy Builder provides a structured way to specify strategy logic, while the Backtesting Lab helps review historical outcomes under selected test configurations.
Those capabilities make testing easier to organise, but a detailed report cannot independently prove that the underlying historical universe is free from bias. Traders still need to understand the symbols, market coverage, corporate actions, and other data assumptions that affect their research.
Further examination using the Simulator or Paper Trader can help reveal how a strategy behaves under additional conditions. These are complementary validation steps, not a correction for missing historical data.
The aim is to keep the test understandable and its limitations visible before placing confidence in its results.
Questions Worth Asking Before Trusting A Backtest
When reviewing a strategy that selects from multiple securities, ask how the candidate list was produced. Was it reconstructed for every historical date, fixed at the beginning of the period, or copied from today's market? Does the dataset include instruments that later stopped trading, and are mergers, symbol changes, and delistings handled consistently?
Also ask whether every selected instrument was genuinely eligible on the date when the strategy claims to have traded it. If that cannot be established, the limitation should appear alongside the performance interpretation rather than being buried in the research notes.
A backtest becomes easier to trust when you can explain both the trading rules and the historical instruments those rules were allowed to trade.
The Bottom Line
Survivorship bias can make a backtest misleading before the first entry condition is even evaluated. A strategy may use reasonable rules and realistic execution settings yet still be tested against a historical universe shaped by knowledge of which companies survived.
For index-based, stock-selection, and ranking strategies, reviewing historical membership and missing instruments is therefore a basic part of sound validation. When accurate point-in-time data is unavailable, the responsible choice is to describe that limitation clearly and avoid claiming more than the test demonstrates.
An honest backtest does not need to pretend its data is perfect. It needs assumptions that can be seen, questioned, and understood.
Before trusting the next impressive result, ask a question that does not appear on most equity curves. Could this strategy really have selected these instruments at the time?
Comments
Ask a question or leave feedback. Guests can post too.
Max 2000 characters.
No comments yet.
Quick answers
What If Point-In-Time Data Is Unavailable?
For many retail traders, complete historical constituent lists and delisted-security datasets are difficult to obtain. That does not make every test worthless, but it should change how confidently the result is interpreted. If you tested only today's constituents, describe the result that way. Do not present it as though the strategy selected from the historical index membership at each point in time. Where possible, compare results across different available universes and review whether the apparent performance depends heavily on a small set of eventual winners. You can also evaluate the finished strategy on data that was not used during development, then observe it on a clearly specified current universe in paper trading. These steps provide additional evidence about subsequent behaviour. They do not repair the missing companies in an older historical test, and they should not be presented as a substitute for point-in-time data. The useful habit is to keep the limitation visible and match the conclusion to the evidence.
Does This Matter For Every Strategy?
Survivorship bias is especially important for strategies that rank, screen, or select among many instruments. In those systems, the available candidate universe directly affects which trades can appear in the backtest. For a strategy intentionally developed for one named instrument, historical constituent membership may be less central because the test does not claim to reconstruct a broad selection process. Even then, the reason that instrument was chosen deserves scrutiny. If a trader tested only today's most successful stocks and highlighted the strongest result, the research process can still contain selection bias. It helps to distinguish the quality of the backtest for a chosen instrument from the quality of the method used to choose that instrument in the first place.